How to Write an Investment Policy Statement – A Guide to Help Keep Your Investments on Track
Every investor should have an Investment Policy Statement (IPS). This guide will show you how to write an IPS to help guide your investment strategy through any situation, including bull markets, bear markets, volatile markets, and any other situation.

Why trust The Military Wallet? We’re a veteran-founded resource that has helped millions make strong financial decisions.
Advertiser Disclosure: The Military Wallet and Three Creeks Media, LLC, its parent and affiliate companies, may receive compensation through advertising placements on The Military Wallet. For any rankings or lists on this site, The Military Wallet may receive compensation from the companies being ranked; however, this compensation does not affect how, where, and in what order products and companies appear in the rankings and lists. If a ranking or list has a company noted to be a “partner,” the indicated company is a corporate affiliate of The Military Wallet. No tables, rankings, or lists are fully comprehensive and do not include all companies or available products.
The Military Wallet and Three Creeks Media have partnered with CardRatings for our coverage of credit card products. The Military Wallet and CardRatings may receive a commission from card issuers. You can read more about our card rating methodology here.
Opinions, reviews, analyses & recommendations are the author’s alone and have not been reviewed, endorsed, or approved by any of these entities. For more information, please see our Advertising Policy.
American Express is an advertiser on The Military Wallet. Terms Apply to American Express benefits and offers.
Do you have an Investment Policy Statement (IPS)? If not, you are missing out on one of the key ingredients of a successful investing career.
An Investment Policy Statement is a written statement of your investment goals and objectives that helps you stay on track, no matter what the markets do. And every investor should have one – whether you’re just starting as an investor or you have weathered multiple bull and bear markets.
Investing is complicated, and having a written Investment Policy Statement will save you time, money, and energy. This is nothing new. Many industries have written policies and guidelines. You have probably used them many times in your career.
I first encountered detailed written guidelines while working in the US Air Force. We used Technical Orders, or T.O.s, every time we performed aircraft maintenance. As you can imagine, aircraft maintenance is highly technical, and mistakes can have serious consequences. That is why we were required to use T.O.s when performing maintenance. Following those manuals ensured we used only prescribed repair methods and didn’t skip any steps. This produced safer and more consistent results. I do the same thing in many areas of my life today, including running my business and managing my investment portfolio.
Let’s take a detailed look at Investment Policy Statements: what they are, why you need one, the benefits, how to write your IPS, how often to monitor it, when to make changes, and more. Buckle up: this 4,000-word guide will show you everything you need to know about writing your IPS!
Benefits of an Investment Policy Statement
An IPS offers many benefits. Investing can be complicated, and your IPS will guide you no matter what happens in the stock market or around the world. Here are some of the benefits of creating and following an IPS:
Separate Your Decision-Making from Your Action Taking
As a small business owner, I create and follow business rules to ensure I stay on track. These business rules produce more consistent results with fewer resources. It makes sense when you think about it – written business rules mean you don’t have to rethink every decision.
You simply refer to the guidelines you created and follow the steps you have already decided to take.
Investing means you don’t need to reinvent the wheel each time you contribute to your 401k, IRA, or brokerage account. You don’t need to spend half an hour analyzing stocks or rebalancing your portfolio before buying a stock or mutual fund. You have already made your decisions. Your IPS is there to follow.
But here is the key: Separate these two actions. Make decisions when you’re clear-headed and not under pressure. Coupling investment research and analysis with an investment decision often overwhelms you. Take the time to document your Investment Policy Statement, and you’ve already done the heavy lifting. Then take action and adjust as needed.
Your IPS Solidifies & Defines Your Investment Goals
Writing your investment goals on paper makes them real. There is a huge difference between saying, “I want to retire someday,” and “I want to retire at age 55.”
The first statement is vague, while the second is a SMART Goal (specific, measurable, achievable, realistic, and time-based).
Your IPS will also include the investments you will use to reach your investment goals. This is helpful when you are thinking about investing in the next big thing – Bitcoin or other cryptocurrencies, binary options, the next big IPO, etc. Is this in your IPS? If so, then go for it if it otherwise meets your investment objectives. Otherwise, skip it and rest easy knowing you are investing within your defined plan.
Your IPS Removes Emotion from Investing
Investing is fun when you’re winning and terrible when losing. Unfortunately, mixing emotions and investing is never a good idea. Once you let emotion rule your investing decisions, your judgment becomes clouded and your likelihood of losses increases.
Developing and using a written Investment Policy Statement will help you reduce emotion’s role in your investment decisions. An investment policy statement codifies your goals and strategy, giving you a plan to follow as you manage your portfolio, no matter how large it is.
Your investment policy statement can provide guidance, and it’s a great tool to fall back on when you start getting nervous about your portfolio.
Downsides to not using an Investment Policy Statement
Without an IPS, you leave your investments to chance. You’re submitting to the whims of your emotions and how you “feel” you should be investing. You will be more likely to chase returns and invest in the hot sectors instead of taking action toward your goals.
In short, you will be shooting from the hip instead of taking precision aim. There is a time and place for spontaneity. Investing isn’t that time or place.
Elements of a Strong Investment Policy Statement
An Investment Policy Statement does not have to be complicated. But it does need enough information to keep your investments on track. Let’s take a look at what you need to write a good IPS:
- Investment Objectives & Investment Timeline
- Risk Tolerance
- Asset Classes to Invest in (and Which to Avoid)
- Asset Allocation Targets
- When to Rebalance Your Portfolio
- Monitoring Frequency (and When You Will Make Changes to Your IPS)
These seem like a lot, and they are. But you can simplify each of these and, in some cases, boil them down to one or two sentences. The simpler you make it, the easier it will be to review your IPS and stay on track.
Let’s take a look at these in greater detail:
Investment Objectives & Investment Timeline
When writing your investment policy statement, start by identifying your long-term goals. What do you want your money to do for you? Whether you plan to buy a home or save for retirement, define the goal.
As I wrote above, your Investment Objective could be as simple as, “to retire at age 55.”
Most of us have more than one goal, so you can expand on this. Try to prioritize your investment objectives when you write them. This will remind you which goal matters most. In the example below, we list retirement savings above and saving for children’s college. We all want the best for our children, but they can always borrow to pay for college. You can’t borrow your way through retirement. So keep this in mind when creating your Investment Objectives.
Example Investment Objectives:
- Objective 1: Retire at age 55 or earlier
- Objective 2: Have investments support annual withdrawals of $50,000 per year, based on a 4% withdrawal rate ($2,000,000 investable assets)
- Objective 3: Pay for 50% of children’s college tuition (assuming tuition will cost $10,000 per year).
- Objective 4: Maintain 6 months of living expenses in liquid funds at all times as emergency funds (assuming $5,000 per month of living expenses).
As you can see, each of these objectives is listed as a SMART Goal and prioritized according to importance. (OK, maybe it’s not listed exactly as a SMART Goal, but the writer will know their age, when their children will attend college, and other information to fill in the gaps.) The key is to define what matters to you and list your investment objectives in specific detail.
Take some time to think about your investment objectives. These online retirement planning tools can help you build a realistic retirement timeline.
Only Include Goals You Are Actively Pursuing. Include any financial goal that matters to you, such as paying off debt, saving for a home, taking a vacation, investing in a business, or anything else important. Remember – this isn’t a dream sheet that lists everything you “want to do one day.” These are the actual goals you are working toward.
Risk Tolerance
Now that you know your investment goals, consider your risk tolerance. Your risk tolerance should reflect your time horizon and what you can financially handle. This should include your emotional risk tolerance.
Many people believe they are more risk tolerant than they are. As I mentioned above, investing feels great while you’re ahead, but even worse when you start losing money.
The key is to balance stocks, bonds, and other securities to achieve growth and stability.
Once you know your risk tolerance, use it to guide your investment choices. Avoid investments that are too risky for your tolerance level, no matter how exciting they seem. Also, recognizing that you may be too averse to risk can help you create a plan to address it and grow your wealth more effectively.
Your Risk Tolerance will directly impact your Asset Allocation (see below for more information).
Asset Classes to Invest in (and Which to Avoid)
Asset classes are the building blocks of your investment portfolio. Asset classes group similar securities and often correlate in the marketplace. They often follow the same laws, regulations, and tax rules.
There are three main categories of asset classes, including stocks (equities), bonds (fixed income), and cash or cash equivalents. Some investors include real estate, precious metals, and commodities as asset classes.
You can further categorize asset classes based on their underlying securities. For example, you can group US and International stocks under equities.
Here is an example of the types of investments you may wish to include in your IPS, and some you may wish to avoid. You can include specific funds if it makes things easier.
Asset Classes to Invest In:
- US Stocks (US Total Stock Market, S&P 500 index)
- International Stocks
- US Government Bonds (Treasury Bonds, TIPS)
- US Corporate Bonds
- International Bonds
- Real Estate Investment Trusts (REITS)
- All of the above should be held in low-cost index funds, when available
Asset Classes to Avoid:
- Individual Stocks / Company Stock
- Actively Managed Mutual Funds / Hedge Funds
- Commodities
- Precious Metals
- FOREX (Currency Trading)
- Cryptocurrencies
The types of asset classes you list to invest with, or avoid, can include stocks, bonds, mutual funds, ETFs, Real Estate Investment Trusts (REITS), investment real estate, precious metals, commodities, and other investments. Just make sure they meet your investment objectives.
Why this section is important: Writing down the types of investments you will use to reach your investing objectives helps keep you on track. Sticking to your plan makes it harder to get caught up in investment hype. Hot sectors, new asset classes, and popular investments will always appear. Avoid trying to hit a home run with every investment. Play the long game. With investing, slow and steady wins the race!
Target Asset Allocation
Use your investment goals, timeline, risk tolerance, and the asset classes you defined above to create your personalized asset allocation guidelines. Your goal is to define how much of your portfolio should be in stocks, bonds, and cash.
This should be done in two steps:
- Define your asset allocation (percentage in stocks, bonds, and cash equivalents)
- Define your asset targets by type (percentage of stocks by type; percentage of bonds by type)
Step 1 – Asset allocation (percentage of stocks and bonds): This is what many people think of when they hear the words asset allocation. What percentage of your investments will be in stocks, bonds, etc.? For example, if you are young, you might want an 80/20 portfolio: 80% in stocks and 20% in bonds. You may want a more conservative portfolio as you get older. Over time, you might transition from 80/20 to 75/25, 70/30, 65/35, 60/40, etc.
Don’t know what your percentages should be? This depends on your investment timeline (how long until you need the money) and your risk tolerance. If you still don’t know, a good place to start is Target Date Retirement Funds, which are designed with a specific retirement date in mind. They automatically allocate based on the target retirement date and are generally a decent starting point. Just use them as a starting point. You should determine your own risk tolerance.
Step 2- Asset Targets by Type: This is where you define how much of each type of investment you have in your portfolio. You can do this by combining the Assets You Will Invest In with your Target Asset Allocation percentage. Let’s look at an example:
Let’s say your target is an 80/20 portfolio with the assets listed in the above section. It could look something like this:
Target Asset Allocation by Type (80/20): (Note: the total percentages should equal 100%, with stocks accounting for 80% of your investment portfolio. In this example, we treat REITs the same as stocks. You can also break the categories down into subcategories, as shown in this example.
- US Stocks – (45% – 30% large cap, 15% small cap)
- International Stocks – (25% – 15% developed, 10% emerging markets)
- US Government Bonds – (10% – 5% Treasuries, 5% TIPS)
- US Corporate Bonds – (5%)
- International Bonds – (5%)
- Real Estate Investment Trusts (REITS) – (10%)
- All of the above should be held in low-cost index funds, when available
As needed, you can change these percentages to meet your risk tolerance and investment objectives. For example, some investors think it’s OK to hold all their equities in US-based markets, while others believe they should have some international stock exposure. Neither is technically right or wrong – only right or wrong for your asset allocation model and thus for your IPS.
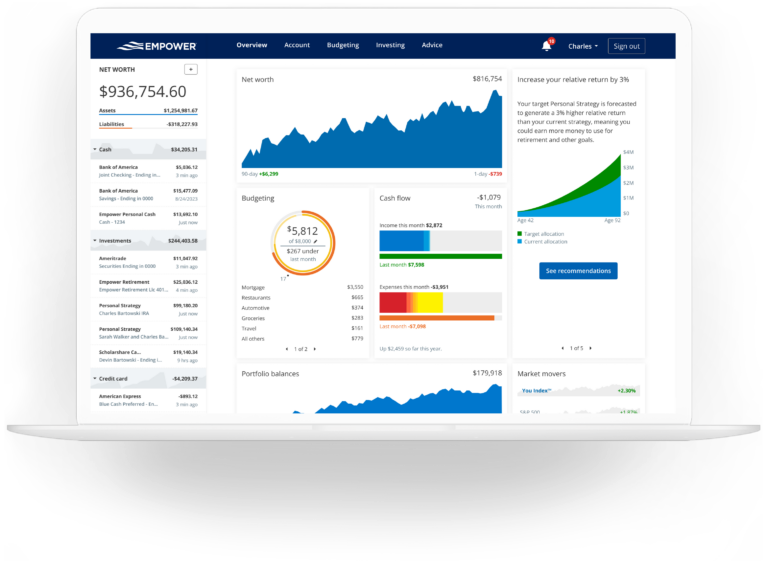
The easiest way to keep your asset allocation on track: Managing an investment portfolio can be tricky, especially when your money is spread across different investment accounts (401k, IRA, taxable investments, etc.).
I use a free online investment portfolio management tool called Empower (formerly Personal Capital). Empower offers a free portfolio analysis tool that securely links to your investment accounts and banks to help you understand how each asset in your portfolio works together. It’s an excellent tool. I use it each month when updating my net worth spreadsheet.
When to Rebalance Your Investment Portfolio
Your investment portfolio will change over time. When your portfolio is small, your contributions can push your assets outside their targets. Don’t worry about this too much when you are younger. Over time, your portfolio will grow, and your contributions will make up a smaller percentage of it, so each contribution has less impact (but don’t stop contributing; compound interest is an amazing force!).
Watch for changes in your investment portfolio due to market fluctuations. A mix of stocks and bonds is meant to reduce portfolio volatility and smooth returns. Sticking to your asset allocation forces you to sell high when you go over your target allocation and buy low when you fall short.
For example, if your target stock allocation is 80/20 but a recent run-up pushes it toward 90/10, you would sell 10% of your stocks and buy an equivalent amount of bonds to bring it back in line with 80/20.
When should you rebalance your investment portfolio? There are two schools of thought, and both work well.
- On a set schedule, such as once per year (your birthday is a good day)
- When your asset allocation exceeds a predetermined threshold (for example, more than 5% outside of your target).
1. You can use any date for a scheduled rebalance. Many people suggest not doing it at the beginning or end of the year because a lot of money enters the market during those times, as many people are funding IRAs or other investments. My birthday is more toward the middle of the year, so that works for me.
2. When your portfolio exceeds a predetermined threshold. In this case, if your target allocation is 80/20, you wouldn’t rebalance until it reaches 85/15 or 75/25. At that point, you can make trades to bring your portfolio back in line.
Note: Don’t forget that asset allocation can and likely should change over time. You need to shift your asset allocation as you approach your investment goal. Create a timeline for changes to your asset allocation as you progress through life. Knowing what you plan to do next will help you stick to your investment objectives and risk tolerance.
Writing this down is also a good idea so you don’t react to market moods. For example, you don’t want to ratchet up your stock allocation when things are going well (buying high), then swing the other way and add more bonds when stock markets decline (selling low).
How Often Should You Monitor or Change Your IPS?
Your Investment Policy Statement should be a living, breathing policy. Review it regularly and update it as needed. Your investment objectives will likely change as your personal and professional life changes. A lot can happen in just a few years – marriage, divorce, having children, becoming an empty-nester, getting promoted, losing a job, getting a raise, losing your job, starting a business, selling a business, relocating, winning the lottery, losing a loved one. The list is endless; any of these can change your goals and objectives.
When to review your IPS: I recommend reviewing your IPS at least once a year, or whenever you experience a major life event.
You may not need to change your IPS. But regularly reviewing it will remind you what matters to you and why. The why is just as important, if not more so than the what. Regularly reviewing your IPS will also help you stay on track. This matters when things are going great and you may feel like taking on more risk, and it matters even more when the markets tank and you may be tempted to sell low.
Just be careful not to make changes based on emotion. Consider creating a time limit before acting on changes, such as 3 months or 6 months. That will give you additional time to reflect upon the current situation and avoid making emotional investing decisions.
Other Considerations for Your IPS
Tailor your IPS to your needs. You can use the information in this guide to get started. But ultimately, your IPS should reflect your investment goals, timeline, risk tolerance, and needs.
You may wish to consider other factors that may influence your IPS, such as:
- Any pensions or annuities and how they might affect your risk tolerance or asset allocation
- Any life insurance policies you may have
- Social Security Retirement Benefits
- How you wish to prioritize the order of your investments – such as 401k up to company match, HSA as an Investment Vehicle, Max Out IRA, Max Out 401k, College Savings, Taxable Investments, etc.
- How you will rebalance – I try to rebalance with new investment contributions when possible. Otherwise, I rebalance my tax-deferred retirement accounts to avoid taxable events and paying capital gains taxes.
- Any outstanding debt you may have
- Unusual estate planning needs
It’s important to add these additional considerations to your Investment Policy Statement so you can refer to them when you review your IPS. This will help keep your investments on track and help you avoid costly investment mistakes.
Write Your Investment Policy Statement, Review it, and Sleep Well at Night
Now it’s time to take action. Write your Investment Policy Statement and create an action plan to fulfill your IPS. Start by thinking about what’s important to you. Be prepared to go through several drafts while you determine what is most important, develop your timeline, determine your risk tolerance, and develop your target asset allocation.
Be sure you include your spouse or partner if you have one. This is especially important if you normally manage all the money. You may have a higher risk tolerance than your spouse or vice versa. You generally want to be on the same page and find some middle ground. You also want your spouse to buy in so you’re both working toward the same financial goals.
Start Investing Now – and Follow Your IPS
Now it’s time to get started. Write a plan that sets forth how much you will invest each month, in which accounts you will invest (401k, IRA, college savings, taxable account, etc.) and which assets you will invest in.
In general, I like to prioritize my investments this way:
- 401k up to company match (Always take advantage of free money!)
- HSA as an Investment Vehicle (read why an HSA is an amazing investment vehicle),
- Max out a Traditional or Roth IRA – see where to open a Roth IRA
- Max Out 401k – even if you don’t get a company match
- College Savings – see where to open a Coverdell ESA (like an IRA for college)
- Taxable Investments – see our list of best brokerage accounts
- Long-term savings – see the best online banks with high interest rates
Stick to this order of operations to maximize your tax-deferred retirement accounts and get the greatest long-term tax benefits. Use dollar-cost averaging to make the most of your monthly contributions. Divide up your monthly contribution according to your stated asset allocation strategy.
Base your monthly contribution on your risk tolerance and stated goals.
When written correctly, your Investment Policy Statement should succinctly guide you through your goals and risk tolerance, help you choose an asset allocation, and lay out your investment plan. While this guide to writing an Investment Policy Statement is several thousand words long, you should be able to keep your actual IPS to a single page.
Keep your investment policy statement somewhere you can access it easily and review your policy statement before you make any decision about your portfolio.
Looking for more inspiration? I recommend visiting the Bogleheads forum and wiki for more info on writing your IPS. I found it helpful when I created mine. Their website includes several examples and a forum where people discuss their IPS, why they make certain decisions when writing it, and a lot more on investing and other topics. This is my favorite financial forum.
Are you ready to write your investment policy statement? Roughly, what will it look like? Leave a comment!