What to Know About the COLA Trap
Service members can prevent lifelong pay inversion by retiring in a few select months, thus avoiding what's known as the "COLA Trap". Here's how it works.

Why trust The Military Wallet? We’re a veteran-founded resource that has helped millions make strong financial decisions.
Advertiser Disclosure: The Military Wallet and Three Creeks Media, LLC, its parent and affiliate companies, may receive compensation through advertising placements on The Military Wallet. For any rankings or lists on this site, The Military Wallet may receive compensation from the companies being ranked; however, this compensation does not affect how, where, and in what order products and companies appear in the rankings and lists. If a ranking or list has a company noted to be a “partner,” the indicated company is a corporate affiliate of The Military Wallet. No tables, rankings, or lists are fully comprehensive and do not include all companies or available products.
The Military Wallet and Three Creeks Media have partnered with CardRatings for our coverage of credit card products. The Military Wallet and CardRatings may receive a commission from card issuers. You can read more about our card rating methodology here.
Opinions, reviews, analyses & recommendations are the author’s alone and have not been reviewed, endorsed, or approved by any of these entities. For more information, please see our Advertising Policy.
American Express is an advertiser on The Military Wallet. Terms Apply to American Express benefits and offers.
Why picking the wrong retirement date could cost you a lot of money
Part of the National Defense Authorization Act for Fiscal Year 2014 legalized the failure to apply specific mechanisms to prevent pay inversions in the pensions of uniformed services retirees. These pay inversions can cost retirees tens of thousands of dollars in retirement and are based on the formula for determining a retiree’s first Cost of Living Adjustment COLA for inflation.
This information comes from a widely circulated graduate research thesis by Colonel Douglas J. Fowler, written as part of his Air War College Air University studies, and it forms the basis of much of this article.
Specifically, this formula creates a variable system that punishes members who retire in the first month of a fiscal quarter and at certain times during the year, thus creating a COLA Trap.
Current active duty members can avoid the pay inversion in three ways.
- Retire at the end of the last month of a fiscal quarter
- Avoid a September or a 3rd quarter retirement entirely
- A first-quarter retirement is best, and March is optimal
We’ve summarized Colonel Fowler’s thesis and added new information to clarify how you can avoid this costly mistake.
An example of how costly the COLA Trap can be
If you’re not vigilant in how and when you take retirement, you could be shortchanging you and your family’s retirement income significantly for the rest of your lives.
Consider the following example from Colonel Fowler.
Lt. Colonels Johnny Late and Jane Early joined the United States Air Force on the same day, were promoted to the same ranks on the same days, and completed 20 years of active duty service on the same day. Lt. Colonel Late retired one month later than Lt. Colonel Early, but unexpectedly began receiving a pension $1,000 a year less than Lt. Colonel Early upon receipt of their first Cost of Living Adjustment the January after they retired. Despite all being equal except for serving one month longer, Lt. Colonel Late will continue to receive a smaller pension for the rest of his life.
This shortcoming in the system is not uncommon. From 2000 through 2023, it’s estimated that service member pension payments totaled $272 million less than expected.
Understanding how retirement pay is calculated
Service members can prevent lifelong pay inversion by retiring in a few select months.
The solution lies primarily in fully understanding the High-3 Pension System, also known as the High-36 system. This is because retirees under this system will continue until January 2048, and so few eligible members opted for the Career Status Bonus/REDUX system.
The first Blended Retirement System members began retiring on January 1, 2026.
Servicemembers who entered active duty after September 8, 1980, have pensions calculated using the average of their highest 36 months of base pay. For most retirees, this is the final 36 months of their pay.
After 20 years of service, a member’s monthly pension is 2.5% of the average of their highest 36 months of base pay for each year they have served. For example, serving exactly 20 years results in 50% of the average of those highest 36 months of base pay.
Each year adds another 2.5% of base pay, so retiring after 24 years would result in 60% of base pay. Or, each added month of service beyond 20 years amounts to about a 0.21% increase in retirement pay.
Unless a service member is medically retired, they must retire on the first day of a given month, meaning there are only 12 possible retirement dates in a given year.
In addition to an annual across-the-board percent pay increase in the National Defense Authorization Act, retirees may also receive an across-the-board COLA increase on December 1 each year. The retiree COLA is determined by an automated formula tied to inflation and the Consumer Price Index, not the National Defense Authorization Act.
Your first COLA compares quarters within the same calendar year, unlike all other COLAs, which compare inflation from the same quarters year over year. You will receive your first COLA effective Dec. 1, the same day as everyone else, but because you’ll have been retired for only part of a year, the calculation differs this once. As a result, you’ll get a partial COLA increase.
Working longer might lead a service member to believe that would add up to more money in retirement, but that doesn’t account for the COLA. In the long term, a better initial COLA can add up to more retirement pay than a few more months of active duty service.
An annual COLA is the difference in inflation between two calendar quarters spaced a year apart.
The COLA formula treats all retirees equally as long as they have been retired for over a year. But that is not the case for retirees who have been retired for less than a year.
Because the National Defense Authorization Act governs active-duty annual pay raises and retiree annual pay raises follow an automated inflation-tied formula, retiree pay raises outpace active-duty pay raises in some years.
In years with a very low or no active-duty pay raise and very high inflation, some retirement-eligible active-duty members would have received a higher pension if they had retired a few months earlier. This concept that a retirement-eligible member could have earned a larger pension by retiring earlier is called a pay inversion.
The High-3 System pay inversion and COLA for new High-3 retirees
A 2012 audit revealed a pay inversion flaw in the High-3 system’s COLA for retirees who had been retired for less than a year.
In 2014, Congress passed the annual National Defense Authorization Act. The Act clarified the Tower Amendment, an existing law that applied to High-3 retirees only on the day they retired, not on the day of their first COLA.
This prevented most retirees from seeking to correct inversions and receive retroactive retirement benefits back to 2000, when retirees first started receiving annuities under the High-3 formula.
Since the Act became law, current retirees have no recourse, but active-duty members can make choices to prevent future pay inversions.
The formula for determining the first COLA for High-3 retirees is different than the COLA formula for retirees who have been retired for more than a year.
- If you retire in the first quarter, your first COLA will be the average inflation of the third quarter of the year you retire minus the inflation rate of the last quarter of the prior year.
- If you retire in the second quarter, your first COLA will be the average inflation of the third quarter of the year you retire minus the inflation rate of the first quarter of the same year.
- If you retire in the third quarter, your first COLA will be the average inflation of the third quarter of the year you retire minus the inflation rate of the second quarter of the same year.
- If you retire in the fourth quarter, you won’t receive a COLA that year because you’re only a month or two into your retirement, and the base quarter is subtracted from itself.
For example, under the current system, October 1 retirees are not eligible for a COLA increase for 14 months because COLA increases are based on quarterly inflation statistics. Colonel Fowler’s thesis explains this complicated calculation in great detail on page 10.
The quarterly COLA formula causes pay inversions.
Depending on the month of retirement, a member’s first COLA will take into account the inflation from one of the following:
- between five months and three months prior
- between four months and two months prior
- between three months and one month prior
For example, the first COLA for members who retire on June 1 reflects inflation from the previous January, not June. The first COLA for members who retire on July 1 reflects inflation from June but not from July, August, or September.
These arbitrary quarterly break points contribute to pay inversions for High-3 retirees.
The following chart from Colonel Fowler’s thesis helps visualize retirees’ challenges.
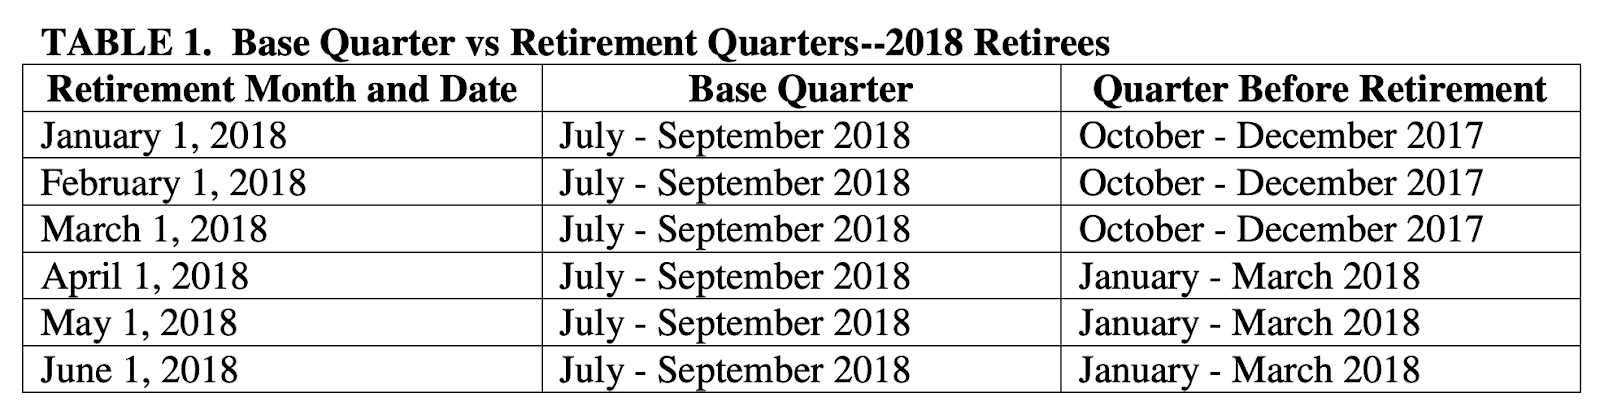
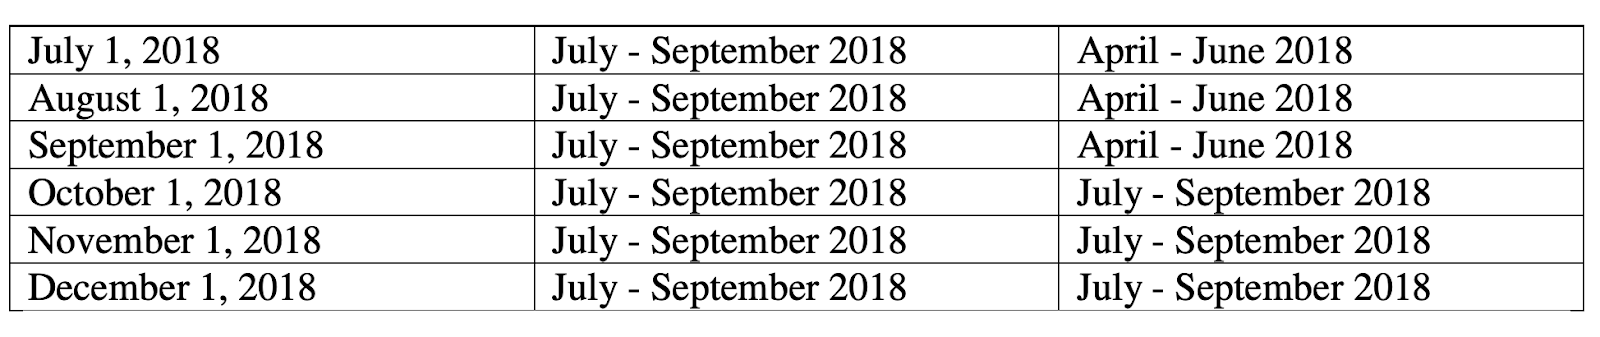
The other cause of pay inversions under the High-3 system is that the formula does not account for inflation spikes or dips between the member’s retirement quarter and base quarter.
The COLA Trap represents a few serious problems. First, it is not fair and makes the government look incompetent.
Second, it will drive members to retire in a month that avoids the pay inversion rather than in a month that best fits the member and the service. A member who otherwise might be willing to retire a month later to help the team would be hesitant if it cost them thousands of dollars over the life of their retirement.
Some experts argue that the pay inversion is insignificant because later retirees received additional months of active duty pay. Fowler cites an example using two colonels who retired in 2011, one in June and the other in July.
As Fowler notes, “The colonel who retired in July suffered a pay inversion but received $9,711 in active duty pay that the June retiree did not receive. This argument is diminished somewhat when we factor in that the June retiree received a $5,754 pension payment while the July retiree was still on active duty. In addition, if we accept the argument that additional months of active-duty pay outweigh pay inversions, then why has Congress consistently fought pay inversions at all? Why is a pay inversion considered bad if it happens between calendar years (which the Tower Amendment remedies), but considered acceptable if it happens within a calendar year?”
Avoiding the COLA inversion trap
Pay inversions don’t happen every year, but because members must give some notice before retiring, they should assume that an inversion will occur in their retirement year and plan accordingly.
Retire in the final month of a fiscal quarter
The best strategy for service members is to retire in the final month of a fiscal quarter to avoid the pay inversion. You’ll get the same initial COLA as if you retired in the first month of the quarter, plus extra pay for longer service.
Members who retire in the first month of a fiscal quarter face the full penalty of retiring in a later quarter: a lower COLA and the minimum fractional years of service available in that quarter.
A later quarter is not guaranteed to have a lower COLA, but as history indicates, the quarterly COLA has never increased in a single year since the High-3 system was initiated.
There is no COLA difference between an April and a June retiree, but the June retiree will receive an extra 2/12ths of 2.5% (about 0.42%) boost to their years-of-service multiplier.
Do not retire in September
Another strategy to avoid pay inversion is to avoid retiring in September, even though it is the final month of a fiscal quarter. This is because a September retiree’s COLA is based on the difference in the measure of inflation between the April/June quarter and the July/September quarter.
Because COLA increases as inflation rises, there isn’t enough time between the April/June quarter and the July/September quarter for inflation to have a real impact. Although September is the worst month to retire, a retirement in any month of the third quarter exacerbates the pay inversion.
Most active duty members do not know there is a separate formula for the first COLA, or even that such a thing exists. If they give it any thought, they logically believe that the first COLA is a prorated portion of the COLA received by those who have been retired for more than a year.
It is logical to assume that January/March retirees should receive 75% of the annual COLA because they have been retired for 75% of the year by the time December 1 arrives, when COLA percentages are determined. Carrying that forward, it’s logical to assume that April/June retirees should receive 50% and July/September retirees should receive 25% of the COLA.
That is not the case. Historical data show that third-quarter COLAs have consistently underperformed other quarters. The formula is not a straightforward and linear calculation of COLA during a given year.
For example, using 2018’s 2.8% annual COLA as an example, many would expect the third-quarter COLA to be at least 25% of that or 0.7%. However, it was only 0.3%, or about half of what was anticipated. By contrast, the first-quarter COLA in 2018 exceeded expectations of at least 75% of the annual COLA, or 2.1%. It turned out to be 2.4%.
First-quarter COLAs are historically above average, with second-quarter COLAs not far behind.
Retire in March
Retiring in March is the third tactic active duty members can employ because March is the one month a year guaranteed to have no pay inversion. That’s because when a member retires in March, the quarterly COLAs for all months of the previous years have already been calculated, applied, and paid out. Instead of being locked into the pension the March retiree earned on their actual retirement date, if that retiree could have retired in any previous month and earned a larger combined pension-plus-COLA amount, they receive that larger amount instead.
A March 1 retirement date has historically provided the best initial COLA, creating the biggest difference between two quarters of average inflation.
Also, March retirees can never have a pay inversion with the preceding January or February because all three are in the same fiscal quarter and will receive the same first COLA in December.