How to Maximize TSP Contributions in a Combat Zone
You can contribute up to $72,000 to your Thrift Savings Plan (TSP) while serving in a combat zone. Discover how to make the most of your TSP contributions during deployment.

Why trust The Military Wallet? We’re a veteran-founded resource that has helped millions make strong financial decisions.
Advertiser Disclosure: The Military Wallet and Three Creeks Media, LLC, its parent and affiliate companies, may receive compensation through advertising placements on The Military Wallet. For any rankings or lists on this site, The Military Wallet may receive compensation from the companies being ranked; however, this compensation does not affect how, where, and in what order products and companies appear in the rankings and lists. If a ranking or list has a company noted to be a “partner,” the indicated company is a corporate affiliate of The Military Wallet. No tables, rankings, or lists are fully comprehensive and do not include all companies or available products.
The Military Wallet and Three Creeks Media have partnered with CardRatings for our coverage of credit card products. The Military Wallet and CardRatings may receive a commission from card issuers. You can read more about our card rating methodology here.
Opinions, reviews, analyses & recommendations are the author’s alone and have not been reviewed, endorsed, or approved by any of these entities. For more information, please see our Advertising Policy.
American Express is an advertiser on The Military Wallet. Terms Apply to American Express benefits and offers.
Expert Reviewed by: Mike Hunsberger, ChFC®, CFP®, CCFC, MQFP, Next Mission Financial Planning
Since many military families already know the basics of contributing to the Thrift Savings Plan (TSP), we’re getting numerous questions about maximizing those contributions during combat deployments.
Military pay is exempt from federal and state taxes for service members deployed in a combat zone, and they’re also eligible for much higher TSP contributions.
I’ll get into the gory details later, but for now, the tax code’s annual contribution limit is $72,000 for 2026. That limit applies even if you’re not in the combat zone all year! Additionally, individuals aged 50 and above can contribute an additional $8,000.
In this article, we’ll walk through examples to show you how to maximize your contributions while in a combat zone and what to keep in mind so you don’t max out your contributions and miss out on DoD matching contributions.
Note: The last sentence means that your higher limits are still available if your deployment is less than a full calendar year.
Key Points
- The Thrift Savings Plan (TSP) is a retirement savings and investment plan designed specifically for military and civil service members. Military members covered by the Blended Retirement System (BRS) receive agency and service matching contributions from the Department of Defense (DoD).
- The IRS sets annual contribution limits for the TSP, allowing members to contribute up to a specific dollar amount each year. One advantage for military members, in particular, is the ability to contribute far more than the annual limit while deployed in a combat (tax-free) zone.
- For 2026, the limit is $24,500 for regular contributions, with an additional catch-up contribution limit of $8,000 for those over 50. However, eligible military members can contribute up to the $72,000 maximum Annual Contribution Limit while in a combat zone.
- I’ve created a free spreadsheet so you can see how this works with your pay. See the example below to see it in action.
Taxes on TSP Contributions: Normal vs. Combat Zone Rules
Under normal circumstances, you contribute to a Traditional TSP with pre-tax dollars, deferring taxes until you withdraw the funds. Contributions grow tax-deferred, but you pay ordinary income tax on both contributions and earnings when you withdraw them.
For a Roth TSP, you contribute after-tax dollars, so while you pay taxes upfront, you can withdraw both your contributions and earnings tax-free if the distribution is qualified.
For service members in a combat zone, the tax treatment of TSP contributions changes significantly. Contributions to a Traditional TSP while in a combat zone are tax-exempt, meaning you don’t pay taxes on them. However, the earnings on these contributions grow tax-deferred and will be taxed as ordinary income upon withdrawal. You can withdraw the original tax-exempt contributions tax-free.
With a Roth TSP, contributions made in a combat zone are also tax-exempt, and you can withdraw both the contributions and their earnings tax-free, provided the distribution is qualified.
2026 Combat Zone TSP Contribution Limits
- Roth TSP contributions before, during, and after your time in a tax-exempt zone count toward the elective deferral limit ($24,500).
- Traditional TSP contributions made before or after being in a tax-exempt zone count toward the elective deferral limit ($24,500).
- Traditional TSP contributions made while in a tax-exempt (combat) zone are listed as “Traditional tax-exempt contributions” and only count toward the annual addition limit ($72,000).
- DoD matching contributions count toward the annual addition limit ($72,000).
Catch-up contributions are allowed for members age 50 or older ($8,000).
What Are TSP Annual Contribution Limits?
IRS rules allow military members to contribute up to the annual addition limit of $72,000 when serving in a tax-exempt zone.
I’ll also answer the question that most of you are thinking about right now:
Hey Nords, I just checked my Leave and Earnings Statement, and, golly dude, I’m not getting paid $72K this *year*– let alone during this deployment. I have expenses, too. Where the heck are people getting the money for this?!
The TSP annual addition limit is the maximum total amount that can be contributed to a participant’s account in a given year from all sources, including contributions from the participant and matching contributions from the DoD.
In other words, that $72,000 limit includes your DoD BRS agency/matching contributions. You’re not actually contributing all of that limit from your pay.
If you’re not part of the Blended Retirement System, you don’t receive government matching contributions, so this number won’t apply to you. But you can still personally contribute up to your elective deferral limit of $24,500.
Finally, you’ll be surprised by how much the DoD and the IRS will help you reach that goal, and this post includes links to confirm it applies to you.
Why Would Anyone Contribute $72,000 Per Year to Their TSP?
Short answer: The TSP has some of the world’s largest passively managed index funds with some of the world’s lowest expense ratios. Depending on how you contribute, you can get tax-deferred compounding and tax-free withdrawals.
You don’t even have to wait until age 59.5 to tap your TSP.
The TSP is one of several investing answers, but it should be a big part of every military family’s asset allocation plan. (Some might decide it’s the best part.) In the combat zone, you’re putting tax-free pay into the TSP. This offers a huge compounding advantage and lets you contribute more to your TSP instead of “contributing” it to the U.S. Treasury’s income-tax fund through withholding and tax returns.
Finally (stay with me here), combat deployments are not exactly fun. (Not even submarine deployments.) We, personal finance bloggers, talk boldly about frugality versus deprivation and work-life balance, but let’s not kid ourselves: this deployment will be more work than life, and a lot more deprivation. As long as you’re embracing the suck, you can still get value from the pain by investing as much as possible toward your financial-independence goal.
For a few of us, maximizing TSP contributions during a deployment is a great way to minimize lifestyle creep after you return. Yeah, you worked hard, and you deserve a nice reward. Instead of a dollar-gobbling, depreciating pickup truck, how about sleeping better at night knowing you’re on track for financial independence? Sure, give yourself a small victory-lap party, but avoid the hedonic treadmill by putting most of that money where it’s hard to frit away.
No worries, this post includes a detailed year-round example. I also have a spreadsheet for you to edit with your own numbers.
Next question: Where are these combat zones located?
Surprisingly, none of them involve actual combat. I hope.
Which Combat Zones Are Eligible?
The DoD and the IRS work with Congress to define combat zones. Here’s the text straight from the IRS press release:
The term ‘combat zone(s)’ is a general term used on IRS.gov and includes all of the following hostile areas where military may serve: actual combat areas, direct combat support areas, and contingency operations areas.”
I was surprised to learn that Djibouti, the Philippines, and even the Sinai Peninsula are eligible for combat zone benefits. The distinction is not whether you’re shooting but rather whether you could be shooting or whether you’re helping other people shoot.
According to the IRS, if you are receiving imminent danger pay or hostile fire pay and your service falls under one of the three scenarios, then you are eligible for Combat Zone pay rules:
- Service in an active combat area as designated by Executive Order, and receive special pay for duty subject to hostile fire or imminent danger as certified by DoD.
- Service in a support area as designated by DoD in direct sustainment of military operations in the combat zone, and receive special pay for duty subject to hostile fire or imminent danger as certified by DoD.
- Service in a contingency operation as designated by DoD, and receive special pay for duty subject to hostile fire or imminent danger as certified by DoD.
Read the fine print in the IRS notice, but if you’re getting that pay on deployment, then you’re probably eligible for the tax code’s annual additions limit to your TSP.
How to Reach The Combat Zone TSP Annual Additions Limit
1. Spread Out Your Contributions
Because the annual addition limit ($72,000) includes government matching contributions, you must reduce your contributions to account for DoD’s 5% match on your base pay.
To make things even more complicated for BRS members, you’ll need to spread your 5% contributions across all 12 months of the calendar year, or you’ll miss some of the match. We touch on this more in the section below.
2. Adjust Your Contribution Amount in MyPay
Here’s another good deal: by the definition of the combat zone, you’re getting more special pay (at least hostile fire or imminent danger pay). You lived without that money in the U.S., and you can probably live without spending it in a combat zone.
Since it’s tax-free, you can set your contribution percentage to 100% to contribute all of it to the TSP. You can do this through MyPay or TSP.gov.
3. See If You’re Eligible for Bonus Pay
Some of you have planned for the next good deal: bonus money. I am not a lawyer, CPA, or CFP, and you’ll need to read your bonus contracts carefully to make sure you’re eligible, but here’s the link: if you sign a bonus contract in a combat zone eligible for CZTE pay, it’s not taxable.
Let’s be clear: I would not volunteer to re-enlist or sign a bonus contract in a combat zone just for the tax-free pay. (Yes, I get reader questions about how to volunteer for this.) I would not even do it to pay off student loans or consumer debt. But if you’re planning to obligate the service anyway, or if you’re eligible for the BRS Continuation Pay bonus between 8-12 years of service, you might as well make the most of your pay advantages as long as you’re in the combat zone.
Suddenly, that annual addition limit might be within your reach.
4. Contribute More Money After You Leave the Combat Zone
Here’s another fine-print point the BRS highlighted: these annual addition limits apply to each calendar year, not just the duration of deployment. When you deploy to a combat zone, you’re eligible for the annual additions limit for the rest of the calendar year. You contribute tax-free pay while you’re in the combat zone, but you can keep contributing taxable pay to the TSP after you leave.
5. Sell Investments From Your Taxable Accounts
Here’s another method that readers have shared with me: sell some investments from your taxable accounts.
Here’s the theory: You’d raise your TSP contributions as high as possible. Meanwhile, you’d sell some investments in taxable accounts and use the proceeds for living expenses. The net result? You’ve shifted a huge amount of money into the TSP and avoided a lot of capital gains taxes.
This is possible because your combat-zone income is tax-free, so your taxable income for the year is very low. Also, when you’re in a low-income tax bracket, your long-term capital gains tax rate is zero.
You’ll want to seek professional tax advice from a CFP or a CPA, but this can save you a lot on capital-gains taxes.
6. Contribute Money From a Loan
One more idea, though it borders on irresponsibility: if you’re a junior officer who took out a career starter loan in college, you can ideally maximize your TSP contributions and live off the loan balance. You’d essentially borrow money at 1%-2% per year to invest in the TSP, then pay it back over a longer term. This is extraordinarily risky (high volatility, loss of principal, leveraged debt) but potentially profitable over a decade or longer.
During my research for this post, I learned that you may even be able to contribute to last year’s IRA. Seek professional advice from a CFP or a CPA before you do this.
Let’s cover some important exceptions to meeting the annual additions limit before we get to the examples.
Combat Zone Annual Addition Limit Exceptions
There are a couple of catches to maximizing your combat zone contributions, and after I published this post, it took me a few more emails with the TSP to confirm them:
- You can not exceed $24,500 in contributions to the Roth TSP at any time during the calendar year.
- When you return home, any further contributions for the rest of the year are subject to the elective deferral limits.
- If your traditional TSP account has already exceeded $24,500 in contributions during the calendar year, you can’t contribute more taxable pay to it.
The Roth TSP Annual Contribution Limit is Still $24,500 In the Combat Zone
Even when you’re eligible for the higher annual additions limit, Roth TSP contributions still count toward the elective deferral limit.
Here’s that crucial fine print:
“Tax-exempt contributions made to the traditional balance of a uniformed services account while deployed to a designated combat zone do not count toward the tax code’s elective deferral limit. However, any Roth TSP contributions are subject to the Internal Revenue Code limit even if they are contributed from tax-exempt pay.”
When you’re contributing to your Roth TSP (and you should), you must stay below the Internal Revenue Code limit ($24,500) until December’s contribution.
This means that your overall annual additions limit will stay just under the elective deferral limit in the Roth TSP (with your last contribution of the year coming in December), and the rest of your contributions will go into the traditional TSP.
Of course, the DoD BRS agency/match contributions are always going into your traditional TSP (see paragraph 7.b.(12) of that link), so between you and DoD, you’ll end up with the rest of your contributions in your traditional TSP account. When your Roth TSP contributions hit $24,500, no matter where you are or when it is during the year, the TSP computer system will cut you off. Any excess contributions from your pay will be used to reach the limit, but the TSP will send the rest back to DFAS. Worse, the TSP will stop contributions at the elective deferral limit ($24,500) and lock you out of contributions for the rest of the calendar year. Which is why you need to leave room for monthly contributions.
BRS Members Should Leave Room For Monthly Contributions To The Roth TSP
The TSP agency confirmed that when you’re home from the combat zone, you can contribute to your traditional TSP only up to the elective deferral limit.
That means if you contribute more than the elective deferral limit to your traditional TSP while in the combat zone, the TSP computers will lock out any further contributions when you get home.
If you’re locked out of TSP contributions before the end of the year, you will lose your DoD BRS matching contributions for the rest of the year.
The solution: When setting up your TSP contributions for the year, start by contributing 5% of your monthly base pay to the Roth TSP. That ensures you’ll have 12 months of Roth TSP contributions and 12 months of DoD BRS matching contributions.
BRS Member Example
Note: The following example was initially published in 2018. For consistency, we have left these numbers as they were in the example provided by correspondence with TSP officials. You will need to update this example to reflect your current situation and maximize your contributions.
This example comes from a series of e-mails with the Federal Retirement Thrift Investment Board (FRTIB), the government agency that runs the TSP, and the DoD BRS office.
The DoD BRS office also asked me to pass this on:
“Individual service members who are impacted by this should contact the TSP call center or a tax adviser for guidance on the impacts of IRS regulations on their contributions.”
Please feel free to refer to this post with the DoD BRS office, DFAS, the TSP, and your pay/personnel office. This example is how the system is supposed to work.
Here’s a scenario for a service member who:
- Opted into the Blended Retirement System or is now covered by default.
- Contributes at least 5% to their TSP every month (for the full DoD matching contributions).
- Deploys to a combat zone to receive combat zone tax-exempt pay.
- Their deployment runs from March to September 2018, and they return home on 1 October 2018.
Here’s the FRTIB response, edited for easier blog post reading:
I think there are many ways that a service member can do this, and I’ll give an example.
Disclaimer: This isn’t advice, just an example of one service member contributing while in a combat zone.
Assumptions:
- A service member makes $48,000/year in basic pay and receives a $30,000 retention bonus while in a combat zone.
- The elective deferral limit is $18,500, and the annual additions limit is $55,000.
Using these numbers, if the service member contributes 5% in January-February and 5% again in October-December, they will contribute $200 per month of their own money and receive 5% agency/matching contributions of $200 per month.
If that happens, the service member will have contributed $1,000 towards the elective deferral limit (their own contributions) and $2,000 towards the annual additions limit (their own contributions and employer contributions).
That leaves seven months in the combat zone to figure out how to contribute.
In this exact scenario, it likely makes sense to contribute to Roth up to the elective deferral limit, minus contributions made in January-February and October-December, because those contributions are tax-free going in and tax-free coming out, as long as you meet all other tax requirements.
In that case, $17,500 remains toward the elective deferral limit ($18,500 minus the $1,000 contributed in the months while not in a combat zone). Divided over seven months, that’s $2,500 per month, plus an additional 5% agency/matching contribution of $1,400.
This brings the total TSP contribution to $20,900, meaning the service member can contribute an additional $34,100 of tax-exempt money to their traditional account. Over seven months, that is $4,871 per month.
These amounts allow the service member to reach the elective deferral and annual addition limits, as well as the maximum matching contribution (5% of $48,000).
Of course, this service member could adjust the numbers to increase contributions while not in a combat zone and decrease them while in a combat zone.
However, if the service member reaches the elective deferral limit before they leave the combat zone, they will not be permitted to make any contributions when they return.
Use a Spreadsheet to Model Your Contributions
As you may have concluded, you’ll need to add this to a spreadsheet to make it clear.
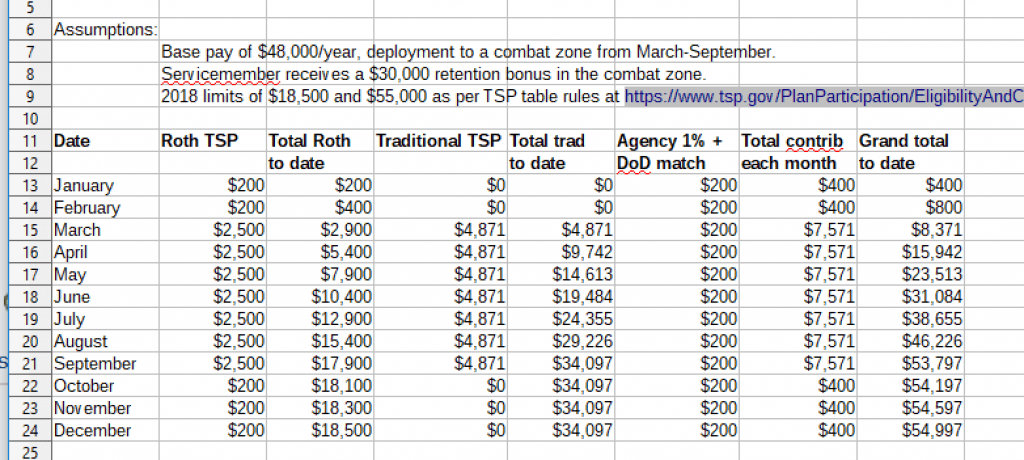
Please note that to edit this spreadsheet, you’ll have to copy it (“File | Download as…”) to your device and then edit your copy.
What If You’re Still In The Legacy High 3 Pension System?
If you’re in the High 3 pension, the rules for your combat zone contributions are the same; you just don’t have to worry about DoD’s BRS agency or matching contributions.
Just remember to stay below the Roth TSP contribution limit, as mentioned in the BRS section.
[Reader question:
“Hello, I read your article about maximizing TSP in a combat zone. I ran into an issue earlier in 2018. Before deploying in June, I had contributed about $18,300 to traditional TSP and $200 to Roth. When I arrived, I couldn’t make any more contributions to Roth, but I could contribute to Traditional. Why is this?”
My response:
If you contributed $18,500 to the TSP before deploying, you’d already hit the elective deferral limit ($18,500 in 2018) before arriving in the combat zone. The TSP computers and DFAS would have locked you out of further contributions.
Now that you’re deployed, neither the TSP nor DFAS would have automatically restarted your contributions. Perhaps someone from your pay office (or DFAS) noted your combat-zone status and restarted the contributions. Since you had already reached your annual contribution limit (and they had to turn it back on), the TSP system wouldn’t accept new Roth TSP contributions for some reason.
I’m sorry this happened. Servicemembers who’ve opted into the new Blended Retirement System or are now covered by it by default are advised not to front-load their TSP contributions so that they can receive the monthly DoD BRS match all year long. This appears to be a similar issue with the TSP computer system.
Note For Servicemembers 50 and Up
If you’re 50 or older, you can include an $8,000/year “catch-up” contribution.
Active-duty folks shouldn’t smirk at this clarification; you’d be surprised how many Reserve and National Guard servicemembers are in their 50s. That should tell you how challenging & fulfilling the Reserve & Guard can be if you’re feeling a little burned out on active duty.
A Friendly Little Note From The IRS
[19 December 2018 update: see a sample IRS letter a few paragraphs below, at the end of this section.]
Several service members (and their frustrated spouses) have reported receiving IRS letters asking them to verify their deployment to a combat zone. One family still received IRS letters about a 2016 deployment, even though the service member deployed again in late 2017.
An IRS computer automatically generates this letter, trying to match the tax return to some report that the service member deployed to a combat zone. (Pro tip: this report to the IRS does not seem to come from DoD.) You’re welcome to call the IRS to confirm, but getting a human to help you respond to the letter is not always easy. I’m not sure an IRS human even sees the letter before it’s mailed to you.
Your best response to the letter requesting your combat zone service dates is a written letter. If you want to be proactive, you can send the letter as soon as you return from deployment. (No operational security issues there!) You can also notify the IRS by e-mail about your combat zone service, but again, I’d wait until you’re home for OPSEC.
Other suggestions include saving copies of your Leave and Earnings Statements for the duration of the deployment.
The whole point of volunteering this information to the IRS is to create an entry in your taxpayer account database that tells the agency you deployed to a combat zone. That way, when your tax return arrives at the IRS months later, the computer will already have a flag in the system to confirm your service. Ideally, it won’t spit out a form letter.
Here’s the IRS’s explanation:
Thank you for your e-mail dated Dec. 10, 201,8 and the information you sent in response to a 2761C letter.
The Department of Defense (DoD) should send us a Combat Zone Indicator (which converts to a Combat Zone Extension in our system) for every military member in a combat zone. The DoD is also supposed to send us a “spousal” indicator if the military member is married. When the military member exits the combat zone the DoD is supposed to send us the exit date.
This system worked well for a couple of decades. Over the past several years, the DoD and our computer systems have had communication issues. Sometimes we get no indicator when a military member is in a combat zone; sometimes we get the entrance indicator but not the exit indicator; and sometimes we get only a spousal indicator.
The Internal Revenue Service is tasked with keeping accurate records for all taxpayers. To do so, we sometimes have to ask our taxpayers for help.
We apologize for any inconvenience we have caused you and sincerely thank you for helping us clean up our records.
You may be interested in Publication 3, Armed Forces’ Tax Guide. You can view it on our website or order it through our toll-free forms line at 1-800-829-3676 Mon – Fri 7:00 am – 7:00 pm your local time.
Your Call To Action
Once again, if you’ve opted into the BRS or are covered by it by default, contribute at least 5% of your base pay to the Thrift Savings Plan each month to receive the BRS match. Even if you’re still paying off debt, it makes sense to contribute to your TSP to at least get DoD’s free money.
Once you know your deployment dates, download the spreadsheet and create your TSP contribution plan. It’d be great to have the income or assets to reach the annual additions limit, but do your best.
Whatever you decide to contribute, make sure you stay below $24,500 in annual contributions to the Roth TSP in 2026, or you’ll be locked out of additional contributions for that calendar year. When you’re in the BRS, that limit lockout will keep you from earning DoD BRS matching contributions for all 12 months of the year.
[The rest of the story:
The FRTIB’s policy isn’t clear in the tax code or in the TSP’s pamphlets and on its website.
I formed this opinion when an AFC and at least three other CFPs could not find a clear reference to the FRTIB’s policy in the tax code or the TSP’s public materials. (Although one of them had seen the TSP’s training materials on the limits.) However, two service members were already locked out of further TSP contributions in 2018. We knew they’d followed the rules on their Roth TSP limits. That meant there could still have been a glitch in the TSP computer system’s BRS software, or another mistake in implementing the legislation. Or… the TSP’s guidance on the annual additions limit was ambiguous.
The FRTIB says that it’s not a computer glitch. DoD’s BRS office (and Congress) can decide how they want the TSP to work. At least one proposal has already been made to change the tax code for Reserve/Guard service members in the BRS who have highly paid civilian jobs with 401(k) plans. My confusion over the annual additions limit seems like yet another unintended consequence of the BRS legislation on TSP contributions.
The good news is that the TSP training team has taken aboard our feedback and is updating their Blended Retirement System training materials. I’ll stay in touch with the TSP and with the DoD BRS office.
Here’s the FRTIB’s verbatim interpretation from one of their TSP Training & Liaison Specialists– one of the people handling the TSP’s Education and Outreach program.
“The answer is “no.” This individual already met their 402(g) elective deferral limit, and therefore would no longer be allowed to make contributions to their TSP (contributions that apply to the 415(c) limit and NOT the 402(g) limit are only CZTE pay contributions, so therefore if you are no longer receiving CZTE pay, any contributions apply to the 402(g) limit, which again, was already met).”
Let me break down that 65-word sentence into smaller clauses.
When you return home from the combat zone, you can still contribute to your TSP accounts– but only up to the elective deferral limit ($18,500 in 2018, $19K in 2019) in each account. The TSP’s website and pamphlets clearly state that you can contribute only combat zone tax-exempt pay above the elective deferral limit to the traditional TSP while you’re in the combat zone. However, they’re not so clear on how you can contribute taxable pay to your traditional TSP after you return home.
One of my smarter friends (a military retiree and a CFP) suggested thinking of it this way: when you’re home, count down from the limits instead of counting up. “How much have I reduced my elective deferral limit in each of my TSP accounts? How much room do I have left to contribute to each one?”
Alert readers will note that the service member in the contribution spreadsheet example received a $30K retention bonus while in the combat zone. If they signed that contract in the combat zone, then every subsequent annual installment of that bonus is also tax-free, even if they’re not in the combat zone. Could they contribute the next few years’ CZTE installments to their traditional TSP up to the annual contribution limit?
My answer: I don’t know. I’ll let the FRTIB and the BRS office clarify those interpretations of the tax code. The good news is that DFAS already knows the bonus contract is tax-free and will reflect it on your W-2.]
Military Guide to Financial Independence
This book provides service members, veterans, and their families with a critical roadmap for becoming financially independent. Topics include:
- Military pension
- TSP
- TRICARE Health System
- & More