Thrift Savings Plan Rollover Guide – How to Transfer Your TSP into an IRA – with Instructions for Tax-Exempt Contributions
Learn how to effectively roll over your Thrift Savings Plan (TSP) into an IRA to maximize your retirement savings, understand the benefits and drawbacks, and ensure you make the most informed decision for your financial future.

Why trust The Military Wallet? We’re a veteran-founded resource that has helped millions make strong financial decisions.
Advertiser Disclosure: The Military Wallet and Three Creeks Media, LLC, its parent and affiliate companies, may receive compensation through advertising placements on The Military Wallet. For any rankings or lists on this site, The Military Wallet may receive compensation from the companies being ranked; however, this compensation does not affect how, where, and in what order products and companies appear in the rankings and lists. If a ranking or list has a company noted to be a “partner,” the indicated company is a corporate affiliate of The Military Wallet. No tables, rankings, or lists are fully comprehensive and do not include all companies or available products.
The Military Wallet and Three Creeks Media have partnered with CardRatings for our coverage of credit card products. The Military Wallet and CardRatings may receive a commission from card issuers. You can read more about our card rating methodology here.
Opinions, reviews, analyses & recommendations are the author’s alone and have not been reviewed, endorsed, or approved by any of these entities. For more information, please see our Advertising Policy.
American Express is an advertiser on The Military Wallet. Terms Apply to American Express benefits and offers.
Before I joined the Air National Guard last year, I decided to transfer the funds from my Thrift Savings Plan account into an IRA. There are many pros and cons to transferring your funds to an IRA, so look at it from all angles before deciding. A Thrift Savings Plan Rollover into an IRA can also be complicated, so get help from an investment professional if needed.
To start, the TSP is one of the best retirement plans available because of its low expense ratios. I previously kept my funds in the TSP because it let me transfer other IRAs or retirement funds into the TSP account later. But since I was going to join the Air National Guard, it didn’t matter whether I closed out my old account, because I could open a new TSP account once I joined the ANG.
I also transferred my funds out of the TSP to move my tax-exempt contributions into a Roth IRA. The tax-exempt contributions were held in a Traditional TSP and were made while I was deployed to a tax-free zone. Since those contributions were made with tax-free pay, they are eligible to be transferred into a Roth IRA – this has huge long-term tax benefits (see below for more information). But I had to liquidate the entire TSP account to access those funds.
First Step – Decide if Closing Your TSP Is Right for You
As I mentioned above, the TSP is a great retirement account because of its low expense ratios. There are no added expenses or fees for keeping your Thrift Savings Account open, so if you don’t have a specific reason to close it, you are probably better off leaving it open. Low fees and flexibility are important in investing.
Additionally, you are able to transfer external funds into your TSP account from other retirement plans, including 401k plans, other TSP accounts, IRAs, and similar plans. You just won’t be able to make new contributions if you are no longer serving in the military or working for the federal government. So keeping your TSP account open can be a good thing if you want to take advantage of the low expense ratios.
Here are some articles to help you make the decision:
- What to Do with Your TSP When You Leave the Government or Military Service.
- Should You Rollover Your TSP into an IRA?
As I mentioned above, in most cases, it makes sense to leave your account open unless you have a specific reason for moving the funds out.
You Decided to Roll Your Thrift Savings Plan into an IRA… Now What?
Once you decide to transfer your funds, make sure you do everything in the right order so the transfer or rollover goes smoothly*. Otherwise, the transaction may take too long to complete. This matters because the IRS could classify the transaction as a withdrawal if you don’t deposit quickly enough. This can include early withdrawal penalties (if under age 59.5), and paying taxes on the withdrawal amount. So enlist assistance if needed.
*Terminology note: The terms “Transfer” and “Rollover” are sometimes used interchangeably with retirement accounts. Transferring an account means moving funds directly from one financial institution to another. A Rollover happens when the funds are sent to the investor, and the investor needs to deposit them into another qualified retirement account within a certain time frame, according to IRS rules. This matters because it can have major tax implications if you don’t do it correctly.
Open an IRA Before You Start Any Other Paperwork
You must open an IRA before you can transfer funds from your TSP. You can ask the Thrift Savings Plan to make the check payable to you, but it’s faster and easier to transfer the funds directly to an IRA you’ve already opened. This also reduces the likelihood of IRS issues.
You will need to provide your bank or brokerage account and IRA account number when you make the funds transfer. If you already have an IRA, you can simply transfer the funds into your current account. If not, you will need to open a new IRA. Start by researching financial companies. We have a list of recommendations here, or you can use any major military financial institution (USAA, NFCU, PenFed) or brokerage house (Vanguard, Fidelity, Charles Schwab, TD Ameritrade, etc.).
Make sure you have both a Traditional IRA and a Roth IRA if you have funds in both the Traditional and Roth sections of the Thrift Savings Plan, or if you want to send your tax-exempt contributions to a Roth IRA (see below for more information about this process).
Complete the Required TSP Paperwork
The next step is to start the paperwork from the Thrift Savings Plan. You can transfer some or all of your funds into an IRA. If you want to liquidate most of your TSP funds but keep your account open, leave at least $200 in your account, the minimum to keep it open. You can then maintain the flexibility to transfer funds into the account at a later date.
To make transfers or withdrawals, you will need to download and fill out the required form:
- Form TSP-70 Request for Full Withdrawal (PDF)
- Form TSP-77 Request for Partial Withdrawal When Separated (PDF)
Then complete the required sections.
Filling Out Form TSP-70 Request for Full Withdrawal. If you are doing a full withdrawal (transfer or rollover of the entire contents of your TSP), then you will need to fill out pages 1, 2, and 4 (Traditional Balance) and/or Page 5 (Roth Balance).
- Page 1 includes your personal information and personal information for your spouse, if you are married. You will need your spouse to sign off on the transfer and have the signature notarized. This security feature ensures both parties agree to the transfer. Many banks provide free notary services to members. Otherwise, check your phone book or the Internet to find a notary public.
- On page 2, section 4, you declare how you want to take the withdrawal, as a single payment, a life annuity, or monthly payments from the TSP. If you are transferring to an IRA, choose 100% for the Single Payment option. You can split this among different options if you choose. Select the Check Box in Section V to indicate you are transferring your assets to another retirement account. Section VII on page 2 requires your notarized signature to authorize the transfer.
- Finally, on Pages 4 and 5, indicate where you want the funds sent. You will need to include the address of your IRA custodian and the account number where you want the funds to be sent. Then your financial institution must complete the remainder of page 4* or 5 (a verifying official must sign the form before the TSP will process it). Then your IRA custodian will fax or mail the completed form to the TSP.
- *See instructions below if you have tax-exempt contributions – this is important because your IRA custodian fills out this section. Instructions below.
- The Thrift Savings Plan will send a check directly to your custodian (for the benefit of your account), and you should deposit it into your IRA.
Filling Out Form TSP-77 Request for Partial Withdrawal When Separated. This process is similar to the above, but the page and section numbers are different. Read through the directions very carefully to make sure you don’t miss anything. If you have questions, call your IRA custodian to walk you through the form. Even if they don’t transfer many TSPs, they should understand enough to help you. If they don’t, then look around for an IRA custodian with better customer service.
Transfer Traditional Funds to a Traditional IRA, Roth to a Roth IRA
It sounds basic, but you want to get this right the first time. When you transfer your TSP funds, make sure you transfer them to the correct account type. This will help prevent IRS issues. Both the TSP-70 and TSP-77 have sections for both Traditional and Roth contributions and transfers.
If you want to convert a Traditional account to a Roth account, do it in two separate transactions. Complete your TSP-to-IRA rollover, then perform a Traditional IRA-to-Roth IRA rollover.
Be Careful with Tax-Exempt Contributions!
If you participated in the Traditional TSP when you were in a tax-free location, you most likely have tax-exempt contributions (this does not apply to the Roth TSP; it only applies to funds in your Traditional TSP account). To verify you have tax-exempt contributions, you should see something like this on your TSP statement:
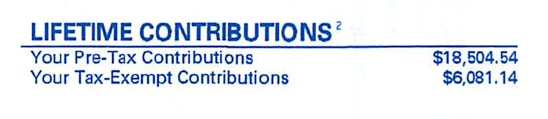
You DO NOT want to transfer these funds into a Traditional IRA. These contributions are tax-exempt, so you can roll them into a Roth IRA. The long-term benefits of this are huge. Here is the difference:
- Contributions to Traditional IRAs, 401 (k) plans, and the TSP are pre-tax contributions, meaning you contribute before your income is taxed. This lowers your taxable income in the tax year you make the contribution. The funds then grow without taxes until you reach retirement age. You pay tax only when you begin making withdrawals.
- Roth IRAs are the opposite. They are considered post-tax contributions. You contribute after paying taxes, and the funds grow tax-free until you withdraw them. You will never pay taxes on those funds again. The law allows military members to contribute tax-free income to a Roth IRA, meaning you never have to pay taxes on that money, either the contributions or the earnings.
In other words, the funds you transfer into a Traditional IRA will be taxed when you withdraw them in retirement, but anything you transfer into a Roth IRA will never be taxed again. Transferring tax-exempt contributions to a Roth IRA gives you years of compounding growth without paying taxes on any gains. This is HUGE.
How to Transfer Your Tax-Exempt Contributions Correctly
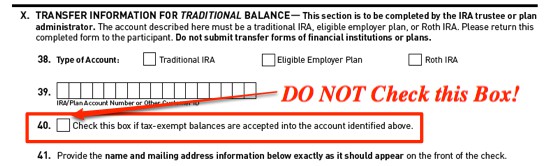
You can prevent your tax-exempt funds from being transferred into a Traditional IRA by NOT selecting the following Boxes in the forms:
Form TSP-70, Section X, Box 40. Do NOT check this box!
Form TSP-77, Section X, Box 36. Do NOT check this box!
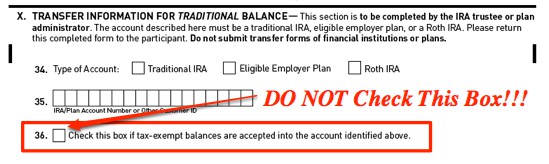
Note: Section X is also the section your IRA custodian fills out to certify you have an open account with them. When I transferred my TSP funds into an IRA, I sent a cover letter to my IRA custodian explaining that I did not want them to check Box 40 on Form TSP-70. I strongly suggest sending written documentation to your custodian to ensure they don’t check this box!
Tax-Exempt Funds are Sent to You as a Check – Be Careful with This! By not checking the box above, you are telling the Thrift Savings Plan that your custodian cannot accept tax-exempt contributions into your account. As a result, the TSP will disburse those funds by check made out to you. This money is non-taxable, so technically you can do anything you want with it, including cash it and spend it. But that would be a long-term mistake since you can roll it directly into a Roth IRA and earn tax-free growth on your investments.
Once you receive the check, send it to your IRA custodian with instructions to deposit it into a Roth IRA. When I sent my check, I signed the back and wrote the IRA account number on it. I also included a letter stating that it was a Rollover from the Thrift Savings Plan. This is important information for the financial institution to note so they can code it correctly for the IRS. Failing to provide this information can cause problems down the road.
Understand the Tax Implications of Your Transfer
In most cases, you won’t have any issues if you transfer funds directly from a Traditional TSP to a Traditional IRA, or from the Roth TSP to a Roth IRA. In both cases, the Thrift Savings Plan will issue you an IRS Form 1099-R at the end of the year (a 1099-R is issued for Distributions From Pensions, Annuities, Retirement or Profit-Sharing Plans, IRAs, Insurance Contracts, etc., PDF). This informs the IRS that you received a distribution from your retirement account.
The company that receives the IRA will issue you an IRS Form 5498 (IRA Contribution Information, PDF). This tax form shows the funds were deposited into another retirement account. These forms help prevent an early withdrawal penalty, taxes, and other nasty surprises.
If you do a Rollover, not a Transfer, make sure the receiving institution codes the contributions correctly to avoid IRS problems. You will still receive IRS Form 5498 if you manually roll over your funds into an IRA instead of doing a direct transfer. Make sure you get a confirmation letter from your financial institution stating they received the funds and deposited them into your IRA.
How Long Does a Transfer / Rollover Take?
As you might guess, this is variable, depending on how busy your IRA custodian is, how long it takes the TSP to process your paperwork, etc. That said, I’ve personally transferred two TSP accounts (one for myself, and one for my wife) and both were completed in less than 2 weeks. But in some cases, it can take up to a month.
Obligatory Disclaimer: There are many factors to consider when transferring retirement accounts. Be sure you consider possible impacts on your tax situation, future retirement planning, etc. You may wish to consult a professional for more personalized and specific advice and recommendations.
5 Things to Consider Before Moving Your TSP After Leaving the Military
Want to learn more? Check out The Military Wallet Podcast discussing what you need to know about transferring your TSP upon retirement.
1. You don’t have to move your money immediately.
You can generally leave your TSP invested after leaving military service. If you don’t have an immediate reason to move the money, consider taking time to get settled into your next job and financial situation before deciding what to do with your retirement savings.
2. Understand your rollover options.
After leaving the military, you may be able to leave your money in the TSP, roll it into an IRA, transfer it to a new employer’s retirement plan, use it to purchase an annuity, or withdraw the money. Each option has different tax implications, investment choices, fees, and rules.
3. More investment choices aren’t necessarily better.
An IRA may give you access to thousands of investments, while the TSP offers a much smaller selection. But a larger menu of investments does not automatically mean better results. The TSP’s relatively simple investment options can provide a diversified portfolio without requiring you to choose among thousands of funds.
4. Compare fees before moving your money.
Before rolling your TSP into another retirement account, compare investment expenses, administrative fees, and any investment-management fees. A retirement account with more investment choices may also cost more.
5. Consider keeping your TSP account open.
Even if you move most of your retirement savings elsewhere, keeping a balance in the TSP may preserve your option to use the account again in the future. Before doing this, check the current TSP rules regarding minimum balances and account status.